
IFRS 17 reporting support in UAE helps insurers turn actuarial output into audited statements and Central Bank submissions that reconcile every quarter. Prima Consulting covers data, models, systems and disclosure, in dirhams.






For insurers already reporting under IFRS 17, the question moves from adoption to repeatability. The strain shows when actuarial output, ledger entries and regulator returns must agree every quarter without a scramble. IFRS 17 reporting support in UAE targets that repeatability.
On 27 April 2026 the ADGM Financial Services Regulatory Authority put final insurance rules into force, including measures to operationalise IFRS 17 for ADGM insurers and reinsurers. Firms in that free zone now answer to a rulebook as well as to the standard. Employee gratuity under IAS 19 is a separate valuation, covered in end of service gratuity valuation in UAE.
| When | Who | What changed |
|---|---|---|
| 1 January 2023 | IASB | Global effective date for IFRS 17 |
| 30 April 2024 | Central Bank of the UAE | Financial Reporting and External Audit Regulation C 5/2023 in force |
| Published guidance | Central Bank of the UAE | IFRS 17 impact assessment template and reconciliation e-forms listed |
| 27 April 2026 | ADGM FSRA | Final insurance rules, including IFRS 17 measures, take effect |
Talent is the other constraint. Few people combine actuarial modelling with IFRS 17 disclosure and regulator reporting, so insurers that build the skill in house avoid renting it each quarter. Neighbouring standards sit with Prima’s IFRS advisory and accounting services practice.
What they need: One reconciled view that finance and actuarial both sign.
Our approach: Prima traces every difference between model output and posted entries to its source and fixes the cause, not the symptom. Good practice benchmarks are in this guide to actuarial practice under IFRS 17.
What they need: Central Bank submissions built from the same numbers as the accounts.
Our approach: Prima maps your IFRS 17 results into the assessment and reconciliation templates the Central Bank lists, so one data set feeds every return.
What they need: Staff who can run the quarter without a call to a consultant.
Our approach: Prima works alongside actuarial and finance staff through live closes until the process is theirs.
What they need: A single inventory of data sources and named owners.
Our approach: Prima rebuilds existing data around IFRS 17 and tests it against the IFRS 17 data requirements, with each transformation logged.
What they need: Models whose period-on-period movements can be explained.
Our approach: Prima's models measure liabilities under whichever approach fits, general model, PAA or VFA, and ship a movement analysis auditors can follow. For the mechanics of the CSM, see the worked CSM example.
What they need: A clear reporting status for the audit committee and the external auditor.
Our approach: Prima's disclosure support and cash flow projections give finance leaders a position they can defend.
| Service | What You Get |
|---|---|
| Reporting gap review | See where reporting practice falls short of the standard and of Central Bank expectations. |
| Data mapping and migration | Policy, claims and reinsurance records made IFRS 17-ready, with lineage an auditor can follow. |
| Systems and integration | Link actuarial engines, the ledger and reporting tools, with Delta where it fits, so returns share one source. |
| Actuarial modelling | Fulfilment cash flows and CSM calculations built on assumptions that are written down. |
| Regulator return support | Map results into the Central Bank templates and e-forms without re-keying. |
| Training for your teams | Teach your people to produce the quarter themselves, with documentation by role. |
| Step 1: Reporting Review |
Prima reviews how actuarial results, ledger entries and regulator returns connect today, and lists every break before any change is made. | OUTPUT: A written findings report with a ranked fix list. |
| >>> | ||
| Step 2: Data Lineage |
Prima traces each input from source system to calculation, fills the gaps and builds a check into every hand-off. | OUTPUT: Validated IFRS 17 data with lineage attached. |
| >>> | ||
| Step 3: Model and Template Design |
Prima configures the models and the mappings to Central Bank templates, built on recorded actuarial assumptions. | OUTPUT: A tested model and a working template map. |
| >>> | ||
| Step 4: Parallel Quarter |
Prima runs one quarter beside current reporting and clears every difference between the two. | OUTPUT: A reconciled close that is ready for audit. |
| >>> | ||
| Step 5: Handover |
Prima stays through a live close, then hands over procedures for every role. | OUTPUT: Procedures in hand and a team ready to repeat the quarter. |
Decades-long contracts bring discount rate sensitivity and slow CSM release into every quarter.
Separate participant funds and surplus treatment, set against the takaful financial regulations the Central Bank still cites.
Whether the premium allocation approach applies, plus onerous contract tests and short-period disclosure.
A clear line between IFRS 17 scope and other standards for bancassurance products.
Ceded contracts measured in line with the underlying direct business, supported by reinsurance consulting.
The FSRA rulebook now includes IFRS 17 measures, so reporting must satisfy both the standard and the rules.
An insurer that closes each quarter with manual workarounds pays later, in audit queries, regulator follow-up and overtime. A planned reporting review costs less than a rework done under deadline, and the list in IFRS 17 implementation challenges shows the usual traps.
Dependency on one person sits underneath it all. When the actuary who owns the roll-forward moves on, the quarter stalls. IFRS 17 reporting support in UAE should leave a process, not a person.
Money spent on IFRS 17 reporting in the UAE buys a steadier close, a cleaner audit file and a calmer regulator relationship, so a query stays a routine reply.

Expect at least one break between model, ledger and return. A free review shows where yours sit in the UAE.
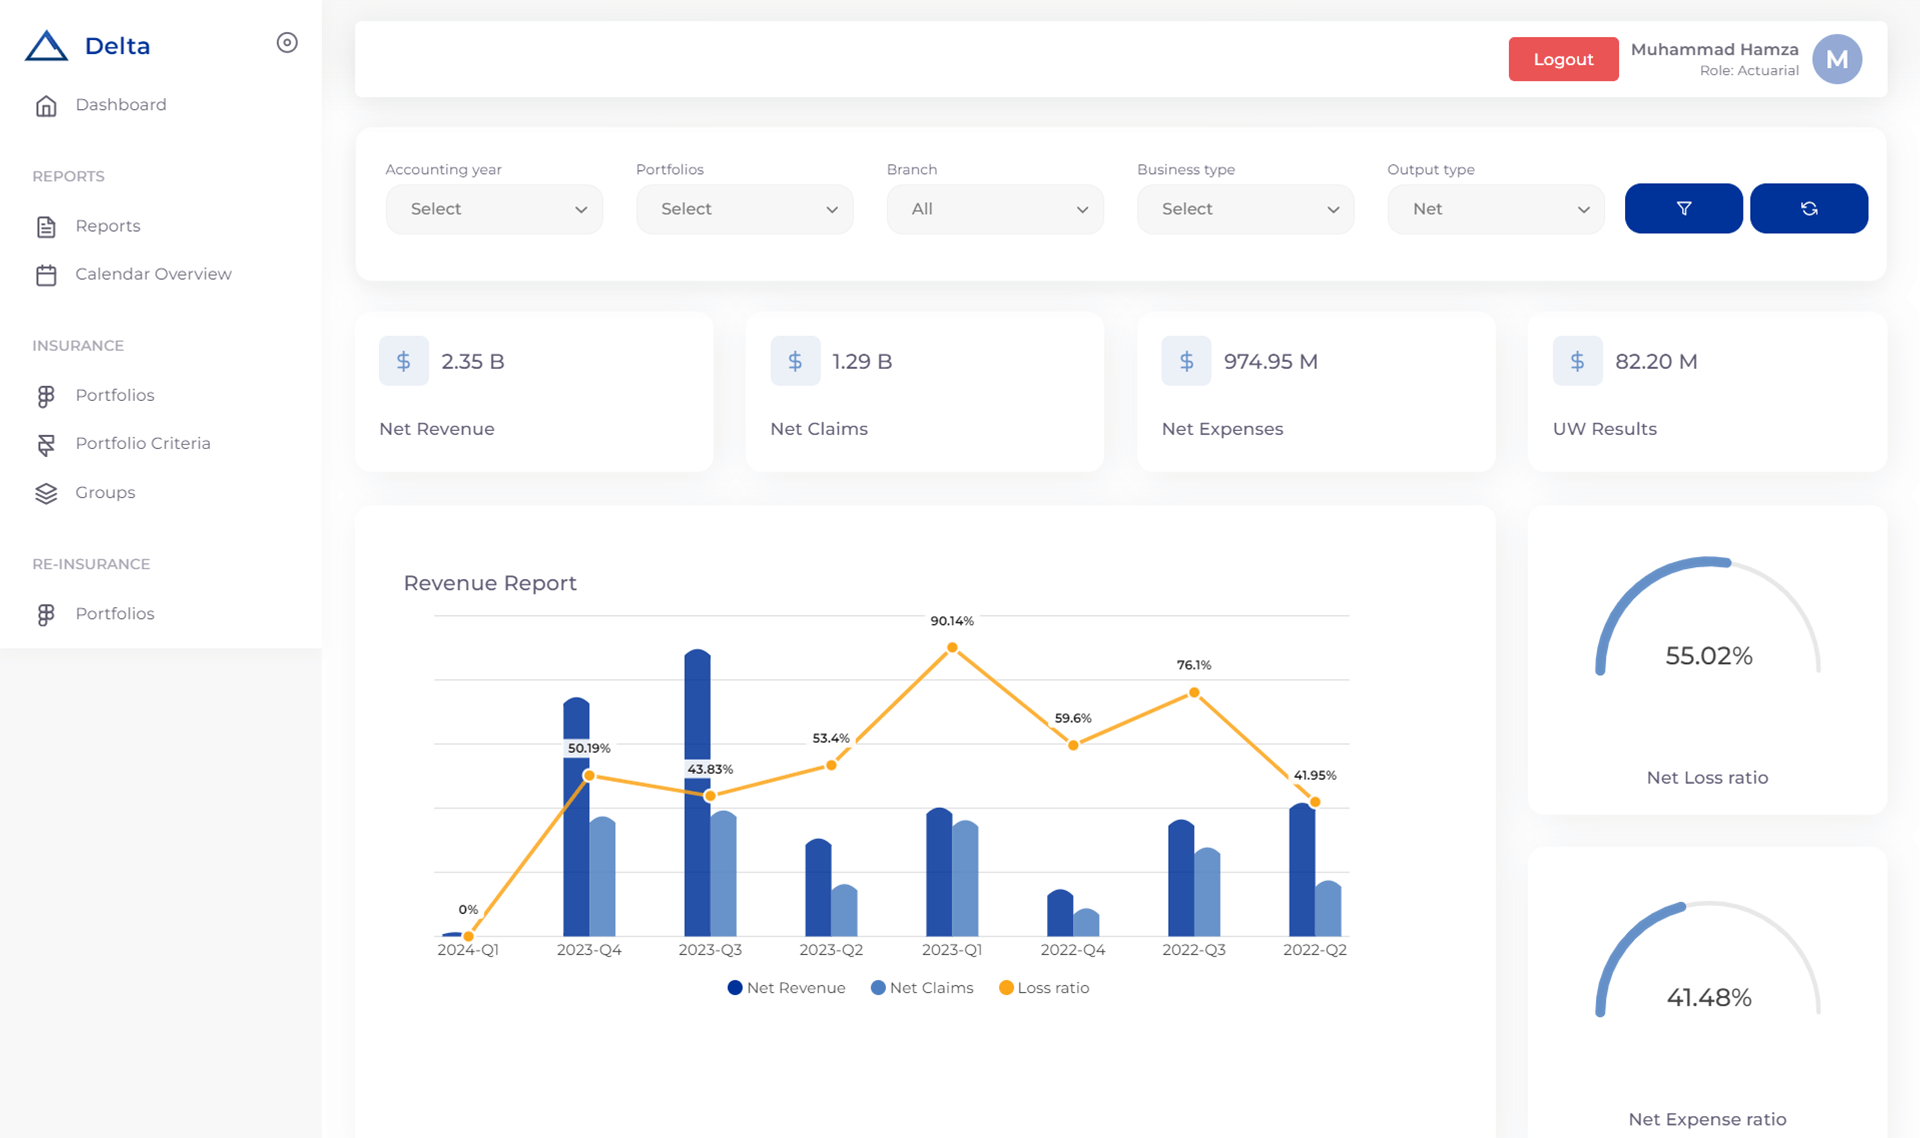
Delta is a cloud platform that gives insurers measurement, CSM and disclosure in a single environment.
The Delta IFRS 17 platform covers insurance accounting end to end, so the quarter runs in house.
IFRS 17 took effect for annual periods from 1 January 2023 and applies to insurance contracts worldwide. UAE insurance companies report under IFRS and Central Bank instructions. A plain-language walk-through is in the IFRS 17 explainer.
The Central Bank's Financial Reporting and External Audit Regulation, C 5/2023, in force from 30 April 2024, requires insurance companies to prepare statements under IFRS and Central Bank instructions and to publish them with an approved auditor's opinion.
The Central Bank's insurance guidelines list an IFRS 17 Financial Impact Assessment template and IFRS 17 reconciliation e-forms. Prima maps your IFRS 17 results into them so returns and accounts come from one data set.
ADGM insurers and reinsurers follow the FSRA rulebook. Final amendments that took effect on 27 April 2026 include measures to operationalise IFRS 17, so firms in ADGM should read those rules alongside the standard.
It covers a reporting review, data lineage, model and template design, a parallel quarter and handover. Prima delivers a written findings report and a ranked fix list in the first weeks.
Book size, contract groups, return count and data rework drive scope. Prima settles scope after the reporting review.
Timing follows data quality and product mix. A reporting review sizes the work for your portfolio, which beats a generic estimate.
Yes. After the project, Prima can run the quarterly process with actuarial and reporting specialists, which is ongoing IFRS 17 reporting support in UAE.
Under the Central Bank regulation, insurance companies publish annual statements with the opinion of an external auditor approved by the Central Bank. IFRS 17 consultants do not replace that audit, and Prima does not provide statutory audit.
IFRS 4 let each market keep its own insurance accounting. IFRS 17 sets one principles-based model for all, and the IFRS 17 and IFRS 4 comparison works through examples.
Yes. Takaful contracts are in scope, and splitting participant funds from shareholder funds adds work that conventional insurers avoid.
Only for insurance products a bank itself writes, never for its banking business. List the product lines first, then see how IFRS 17 and IFRS 9 interact.
One accountable lead sits across both. Finance answers for the published numbers, actuarial for the cash flow models, and the shared data model needs one owner. Prima's actuarial services team names that owner in the reporting review.
Models that are tested now carry less risk when the next return is due. Whether you are cleaning up a first implementation or hardening a mature process, Prima Consulting brings written methods, tested results and audit-ready workings to insurers in the UAE. The full range of work is listed under Prima Consulting services.
Ready to elevate your business with Prima Consulting? Fill out the form below to discuss your needs with our experts and discover how we can help you achieve your business goals.
We Schedule a call at your convenience
We do a discovery and consulting meeting
We prepare a proposal
Regulatory Compliance Notice
Our services are delivered in accordance with applicable laws and regulations in each jurisdiction.
Prima Consulting provides its services and engages in accordance with the local applicable laws, regulations, professional standards, and regulatory requirements of the jurisdiction in which each service is performed.
Thus, our services are delivered through the appropriate Prima network firm, office or, where required, an appropriately licensed or authorised professional partner. Where a service is not to be provided by one Prima Consulting entity, it may be provided through another Prima Consulting entity or an appropriately authorised third party or not at all for some services, subject to applicable laws and regulations and we ensure strict compliance in this regard.
Nothing on this website constitutes a representation that any particular Prima Consulting entity is licensed or authorised to provide every service in every jurisdiction. Regulatory permissions and service eligibility are assessed on a service-by-service and jurisdiction-by-jurisdiction basis. This is done to ensure compliance in the face of changing local and global trends in laws, regulations and standard best practices.
The user of this website by entering accepts that such services shall be sought and procured through official legal channels appropriate and allowed for such service. In case of any ambiguity in this regard, it is strongly advisable to seek help from professionals or our team.